Thursday, April 15, 2010

Method of Action

The Grameen Bank's Method of Action can be illustrated by the following principles:
1. Start with the problem rather than the solution: a credit system must be based on a survey of the social background rather than on a pre-established banking technique.
2. Adopt a progressive attitude: development is a long-term process which depends on the aspirations and committment of the economic operators.
3. Make sure that the credit system serves the poor, and not vice-versa: credit officers visit the villages, enabling them to get to know the borrowers.
4. Establish priorities for action vis-a-vis to the the target population: serve the most poverty-stricken people needing investment resources, who have no access to credit.
5. At the begining, restrict credit to income-generating production operations, freely selected by the borrower. Make it possible for the borrower to be able to repay the loan.
6. Lean on solidarity groups: small informal groups consisting of co-opted members coming from the same background and trusting each other.
7. Associate savings with credit without it being necessarily a prerequisite. 
8. Combine close monitoring of borrowers with procedures which are simple and standardised as possible.
9. Do everything possible to ensure the system's financial balance. 
10. Invest in human resources: training leaders will provide them with real development ethics based on rigour, creativity, understanding and respect for the rural environment.

Thursday, February 4, 2010

Managing the Double Bottom Line in Microfinance

Dr. Sourendra Nath Ghosal , Head (Knowledge Management) , Microfinance Focus

Micro financing institutions have emerged as a successful delivery model to garner savings of poor of course in a limited manner and to fund rural and urban poor to pursue any economic activities to enable them to earn their livelihood. It has been reported to have an average annual growth of 30% and have covered about 68 million people. (Vide STATE OF THE MICRO CREDIT SUMMIT CAMPAIGN REPORT –2003 and subsequent reports of CGAP). So much so good but an in depth analysis would reveal that yet these institutions have to go miles to achieve its ultimate objective of alleviation of poverty of poor and not just remain as an institution to fund immediate trading or farming needs of these people.

Some of the constraints in attaining the above objective that these institutions face as has been pointed out in various research studies (vide Presentations of CGAP & World Bank data) could be summed up as follows:

1. Inadequacy of donor funds particularly when compared to its insatiable demand; in fact one research study has revealed that on an average annual cash flow estimated for this sector is at least $5 billion but in fact donor funding is even below $1 billion;

2. Insufficient flow of funds from the private sectors as most of them consider such investment is risky if not ranked as unsafe;

3. Inadequate state support as most of the state funds are routed through political institutions for obvious reasons;

Above all these institutions source funds from commercial banks at high cost.

It is obvious therefore most of these institutions lend money at high rate of interest and despite this their margin as reported by most of them remain low and therefore they have very poor leverage to maneuver pricing of their products and services to suit the needs of poor, poorer and poorest. Hence the question of alleviation poverty relegates to background and only continuity and sustainability remain as primary or rather sole objective of these institutions. In fact social mission is dumped for obvious reasons by most of these institutions. Furthermore some smart management take advantage of poor people dependence and ignorance of financial natty gritty and impose other charges along with structuring interest rate on flat basis or at monthly rate to hide the higher load of interest they charge on these helpless poor.

It is therefore imperative to help them to source low cost funds to empower them to strategize their business with social mission of alleviation of poverty and also to pursue commercial viability for attaining sustainability which is indeed equally important. This fine tuning is feasible when mindset of state agencies and donor institutions could be changed so that they not only think these institutions are less risky as well more effective both in achieving social and commercial missions.
-more-

Thursday, December 3, 2009

How a Village Saved Its Fishery

How a Village Saved Its Fishery: "A tiny Muslim village in Thailand revived its mangrove trees and brought back its shrinking fish population...." (focus is not on their religion but on their community).

In a tiny Muslim fishing village called Tamarind Cape, a mangrove swamp has been reborn.
Twenty-five years ago it was almost gone. Because Mangrove charcoal is prized across Southeast Asia for its cooking properties, a Thai logging company was making quick use of Tamarind Cape's limited supply of wood. As the swamp that once split the village in two started to shrink, the fisherman began to notice something. Their catch was disappearing too.

"Ninety-seven percent of the 600 people who live here depend on the sea," said Babu Nyansee, a 74-year-old Imam and the village headman of Tamarind Cape. Babu and I were sitting on the banks of an estuary, staring out at surreal towers of limestone that jut suddenly out of the sea in this part of the Thailand. "As the mangroves disappeared, we began to realize that it was affecting the fishery; all the fish we eat come here to spawn. And many of the things they eat do too. So, slowly, we brought the ecosystem back with the help of Yadfon, an NGO based in Trang."
 
The old man spoke slowly and deliberately. Though small and rail thin, he projects considered strength, and as we talked it was clear he was speaking for everyone in his village. Babu is an unlikely conservationist, and a defender of this fishing village's interests.

The success of this small community in Tamarind Cape stands as a model for progress in Thailand's south, where polluting prawn and fish farms patchwork the coast, and many fishermen complain of emptying seas.

As we walked the muddy banks, balancing on palm fronds so as not to slip in the muck, he showed me a tool they're using here: small fish traps that float in the nutrient-rich current heading out of the swamp, where they also farm seaweed. "We used to just throw all our small fish away, or sell them for next to nothing. Now, we put them in these traps, and the grouper grow big and in a few months can sell for 150 baht ($4.50) each."


That's enough to feed a family for a few days.

Later, we cruised Babu's swamp in a longtail boat, past baroque tangles of mangrove roots. An osprey swooped over the river ahead of us, and Babu smiled and traced its path with his finger. It was a peaceful scene.

But just to the south, in the provinces that border Malaysia, a bloody, protracted war is being fought. This insurgency, which officially began in 2004 but has been fomenting for decades, has claimed over 3,500 lives in Thailand. Lately, there have been bombings and shootings in Pattani, Yala, and Narathiwas provinces almost daily, but the conflict gets very little international attention.

We were in Trang Province, a 45-minute drive north of the violence, but here ethnic Malay Muslims and Thai Buddhists appeared to live in relative harmony. I asked Babu why.

"In Trang, in my village at least, Muslims and Buddhists are like cousins. We join in each other's celebrations, we fish together, and we are all pretty satisfied with the role of our government. But in the deep south, people are dissatisfied with the lawmakers, and with human rights abuse on both sides. But there is another reason: The south is very poor. There is no work there, and there aren't that many fish."
To ease the suffering of his ethnic group in this war-torn area, Babu has invited several Muslim village heads to Mangrove Cape to study how to reintroduce these forested swamps. They are also encouraged to practice more sustainable models of fishing in their villages. "It's a small amount of people that we can affect," he admitted, "but a small change can make a difference."

There are many ethnic and political flashpoints in Thailand's southern insurgency, and it shows little sign of letting up. But as we cruised the mangroves, this Imam seemed to think that peace, too, might result from the rebirth of this misunderstood resource.
Thursday, November 19, 2009

Challenges in Youth Livelihoods

Interesting statistics that should compel you to pray and be involved:


  • Recent estimates suggest that developing countries are home to 1.3 billion of the world’s 1.5 billion youth aged 15-24. 
  • While the youth population continues to grow rapidly, economic opportunities in the form of access to education, employment, or entrepreneurship are not growing at a proportional rate.
  • Unemployment rates are much higher for youth than for adults, in some countries up to 7 times as high.
  • According to the 2007 World Development Report, “youth make up 25 percent of the working population worldwide, but 47 percent of the unemployed.”

Demographic shifts caused by the rural exodus to urban areas, stagnant literacy rates, and static numbers of higher education opportunities all contribute to the need for greater attention to youth and their economic prospects. In many countries, unemployment, underemployment and dubious informal sector employment leave much insecurity. All of these factors are leading to heightened concerns about the potential for disaffected and idle youth to participate in potentially destabilizing or destructive activities.
Youth Livelihood

Charitable deductions cap may hurt nonprofits | PRI.ORG

Charitable Deductions Cap May Hurt NonProfits
This is very worrying. We realize the strength of any program is the people implementing changes in their lives because they have been empowered. Yet, external donors always fill the gap and in strategic ways. So, if we begin to see a shrinking economy locally, it will surely shrink globally.

This article points out, "So, if someone were to donate $100,000 to charity, instead of getting a $35,000 tax deduction they are getting a $28,000 tax deduction.  There are many folks out there who are worried ... and on top of the economic situation, is really going to affect giving among high-end donors."

Tuesday, October 27, 2009

Urban Ministry (UM) ... At Work!

Moses Dahirong, from our Abuja office:

Urban Ministry (UM) Abuja continues to work with 25 communities and have been sustained over time. Some new communities have indicated their interest to register and collaborate with UM Abuja. This is because they consider the programs as beneficial with direct bearing on their lives and families. We hope to work with more communities as our resources improve.

There are clear dimensions of transformation being seen in the way the cooperatives; share the vision of Urban Ministry and involvement in self help projects, support church projects like building and support to widows/the needy in the community. They also transfer acquired skills during UM workshops to other members of the community. Community members are becoming more like a family, each willing to care for one another - visiting each other's homes, assistance during crisis and sharing in joys!


Emmanuel Agbinda, from our Lagos office:

UM has directly intervened to change some individual members whose situation was bad and pathetic. We were able to assist a widow without a child who was denied access to her late husband’s farm and small house. She was even stripped of her personal property by the her in-laws. UM was able to fight for her legal rights and she is now able to farm and be sustainable.

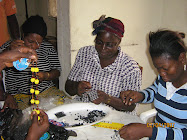
We continue to train members to acquire skills and become self-reliant. Training in bead-making, hats, body lotion, vaseline, cake and confectionaries, soap, etc were taught in several workshops held on small business management.

Monday, October 19, 2009

MFI 101: Basics

ACCESS Microfinance Alliance, or AmFA, (a not for profit organization from India at ACCESSdev.org) has been speaking into the Micro Finance Institutions (MFI) successfully for years.

What is it?
Although the microfinance sector is growing at a fair clip, many small MFIs still grapple to upscale their operations. Due to limitations in governance, management, systems and procedures, the smaller MFIs do not possess enough credibility to attract the financial markets effectively. AmFA’s primary mission is to bridge the gap between the supply and demand and help the smaller MFIs to upscale their operations and thereby expand outreach. While the nature of engagement of ACCESS with each of these institutions varies following the context, the aim is to bring NGO/MFI partners together on a common platform to assess institutional needs for technical support and present an aggregation of demand for on-lending funds to the financial markets.

Products and Services
AmFA adopts a two pronged strategy: while providing need based technical support to its members, it also builds operational and strategic relations with the supply side players to facilitate inflow of funds. In addition to the array of technical services provided to the MFIs, the AmFA members have a privileged access to a wider range of products and services:

Revolving Loan Fund
The platform allows the institutions to have access to a Revolving Loan Fund (RLF), currently housed in CARE. The fund provides “bridge loans” as an interim measure till the MFIs get linked to mainstream markets.

MFI performance analysis and benchmarking
ACCESS analyses AmFA members’ performance indicators, financial statements etc. and publishes the key performance ratios and indicators in an annual publication, MICROSCAN. Providing in-depth and complete financial analysis of partners’ portfolios, MICROSCAN is a part of ACCESS strategy to share partners’ plans and performances with the financial institutions and fostering possible on-lending relationship with AmFA partners.

Facilitation of on-lending fund linkages
Being able to attract investments is one of the biggest challenges for nascent, emerging as well as growing microfinance institutions. ACCESS assists AmFA members in getting linked to commercial banks for investments and on-lending fund support.

Information Dissemination

ACCESS took initiatives to disseminate the respective performance data of its members on large database such as “MIX”, and portals such as “Microfinance Gateway”. Portfolio information of members is shared with financial institutions and published in the “Alliance Directory”. Special individual member achievements are published in “AmFA Line”, a quarterly newsletter.

Followers